WASHINGTON - Airbus and Boeing are largely performing as expected on the narrowbody side in terms of stabilizing and increasing production rates. But widebodies are another story.
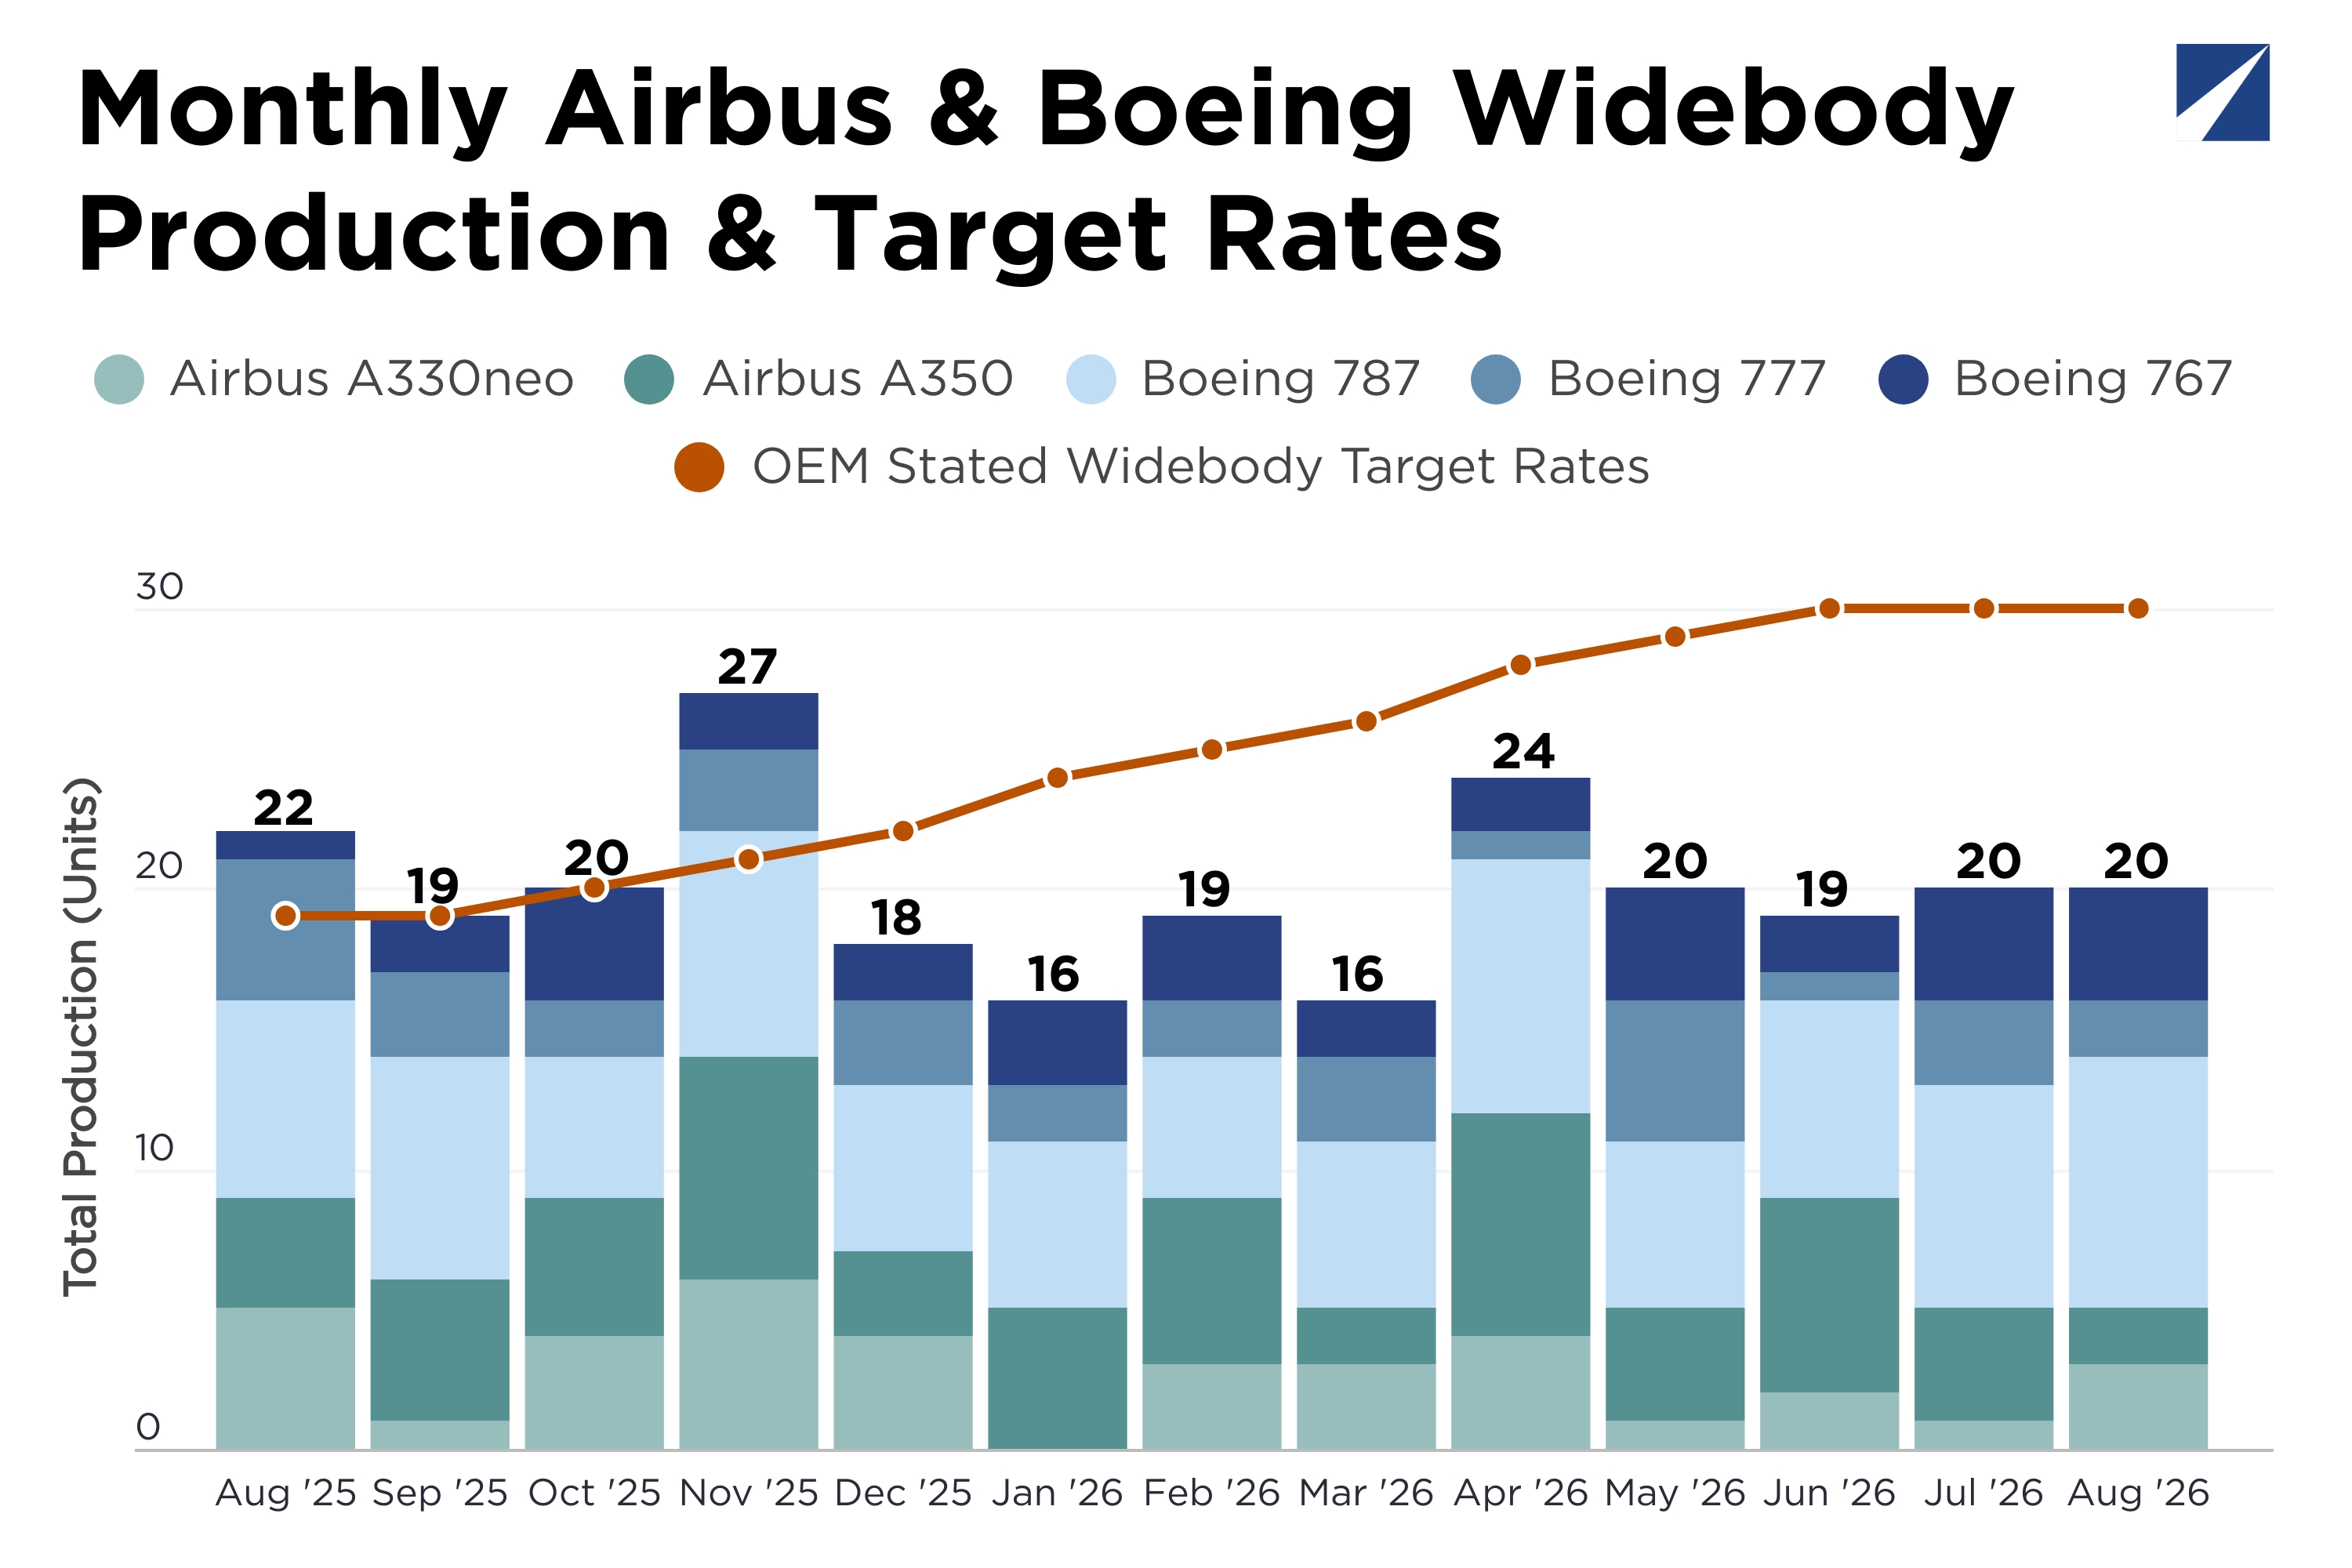
The widebody segment has struggled and remained stagnant, with virtually no production growth over the past year. While neither OEM faces severe execution risk in meeting their annual delivery targets, the widebody segment is dragging down overall performance. As a result, narrowbody programs are effectively having to carry the weight and offset the widebody shortfall.
The A350 program has struggled the most. Heading into 2025, it had stabilized around its target rate of six aircraft per month, with ambitions to reach 10 per month by 2026. Instead, the opposite occurred, and the program is now struggling to stabilize back at six per month, and performance has degraded since mid-2025. The 787 also struggled in late 2025 and early this year after destabilizing from its target rate, though trends are currently improving.
The data in this insight are derived from our Commercial Aircraft OEM Intelligence Brief. For more in-depth OEM and program-specific analysis that incorporates this data and analysis to evaluate the health and execution of commercial aircraft manufacturers, explore the full Commercial Aircraft OEM Intelligence Brief.